
Remortgage Advice
Fixed rate coming to an end? Get tailored, FCA-regulated remortgage advice comparing thousands of deals from 50+ UK lenders to help you avoid costly standard variable rates.
- 50+ UK lenders
- No obligation quote
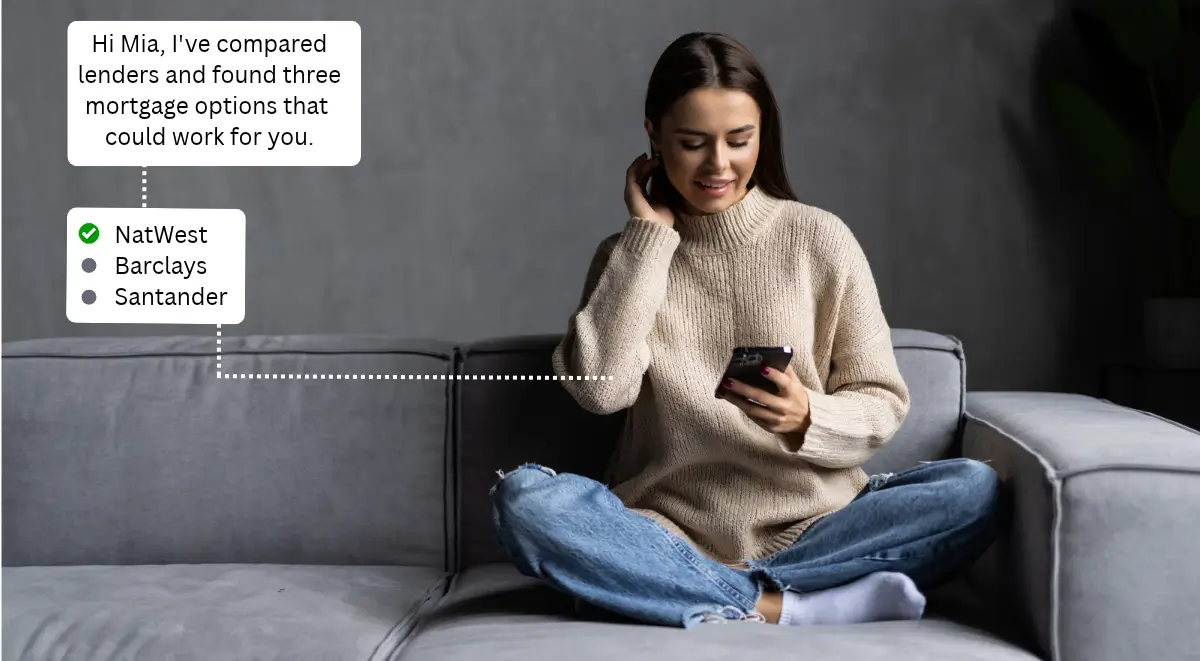
Product Transfer vs Full Remortgage
Which Is Better?
When your current deal expires, you can either switch to a new rate with your existing lender (a product transfer) or move your mortgage to a different lender. Here is how both options compare:
| Feature | Product Transfer (Same Lender) | Full Remortgage (New Lender) |
|---|---|---|
| Rate Selection | Limited to your current lender's retention rates | Access to 50+ UK lenders and intermediary exclusives |
| Credit & Affordability | Usually no new credit checks or income reassessment | Full credit check and updated affordability assessment |
| Legal & Valuation Fees | None—no conveyancing or valuation required | Often covered by free legal/valuation incentives |
| Borrowing More / Changes | Limited flexibility for extra borrowing or term changes | Ideal for capital raising, home improvements, or term adjustments |
| Speed to Complete | Fast—often arranged within days | Typically 4 to 8 weeks (can be locked in up to 6 months early) |
YOUR HOME OR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON YOUR MORTGAGE.
What Affects the Remortgage Rates You Can Get?
Lenders price remortgage deals based on your Loan to Value (LTV) ratio—the percentage of your property's current value that you still owe. If your home has increased in value or you've paid down your balance, you may unlock a lower LTV bracket and cheaper rates.
Lower LTV
Dropping from 85% LTV to 75% or 60% LTV typically unlocks significantly lower interest rates across high-street lenders.
Early Repayment Charges
Switching before your current fixed period ends can trigger an ERC (typically 1%–5% ), which we calculate before recommending a move.
Updated Income & Credit
Moving to a new lender requires up-to-date payslips or tax returns, so keeping credit commitments low in the months beforehand helps maximize options.
| Property Value | Remaining Mortgage | Current LTV | Rate Tier Impact |
|---|---|---|---|
| £300,000 | £255,000 | 85% LTV | Standard higher-LTV pricing |
| £300,000 | £225,000 | 75% LTV | Competitive mid-tier rates unlocked |
| £300,000 | £180,000 | 60% LTV | Access to lenders' lowest headline rates |
The 5-Step Remortgage Process
Starting your remortgage review up to 6 months before your current deal expires lets you lock in a rate early—and switch to a better one if rates drop before completion.
01
Rate & ERC check
We review your current mortgage balance, end date, and any early repayment charges to establish your ideal switch window.
02
Market comparison
We compare your existing lender's retention rates against 1000's of deals across 50+ UK lenders.
03
Agreement in Principle
Once we select the best deal, we secure an Agreement in Principle (or reserve your retention rate) to lock in pricing.
04
Application & Valuation
We submit your full application with supporting documents while your new lender confirms your property's valuation.
05
Legal Switch & Completion
Solicitors handle the transfer on the exact day your old deal expires so you never roll onto a costly Standard Variable Rate.
Reviewing your mortgage?
Check your protection too
If your mortgage balance, term, or family circumstances have changed since you last took out cover, a quick protection review ensures your home stays protected.

Life Insurance
Pays a lump sum if you die during the policy term. This could help repay the mortgage and support a partner or dependants.

Critical Illness Cover
Pays a lump sum if you’re diagnosed with a condition that meets the policy’s definitions, helping with your mortgage, bills or other costs.
Income Protection
Replaces part of your income if illness or injury prevents you from working, after a waiting period and for the benefit period your policy allows.
Popular Reasons Homeowners Remortgage
Whether you simply want lower monthly payments or need to restructure your borrowing, we tailor your remortgage to fit your plans:
Remortgage Advice FAQs
How early can I start looking at remortgage deals?
Is it cheaper to stay with my current lender or switch?
How much does GHL Direct charge for remortgage advice?
Can I remortgage to release equity for home improvements?
How long does a full remortgage take?
Authorised & Trusted UK Mortgage Brokers
GHL Direct is a trading style of GHL Network Services Ltd, an Appointed Representative of The Openwork Partnership (authorised and regulated by the Financial Conduct Authority). Firm FCA reference number: 497119
See how much you could
save on your remortgage?
Speak with a dedicated GHL Direct adviser today. No jargon, no pressure, and appointments available within the hour, 7 days a week.
