
Why Use a
Mortgage Broker?
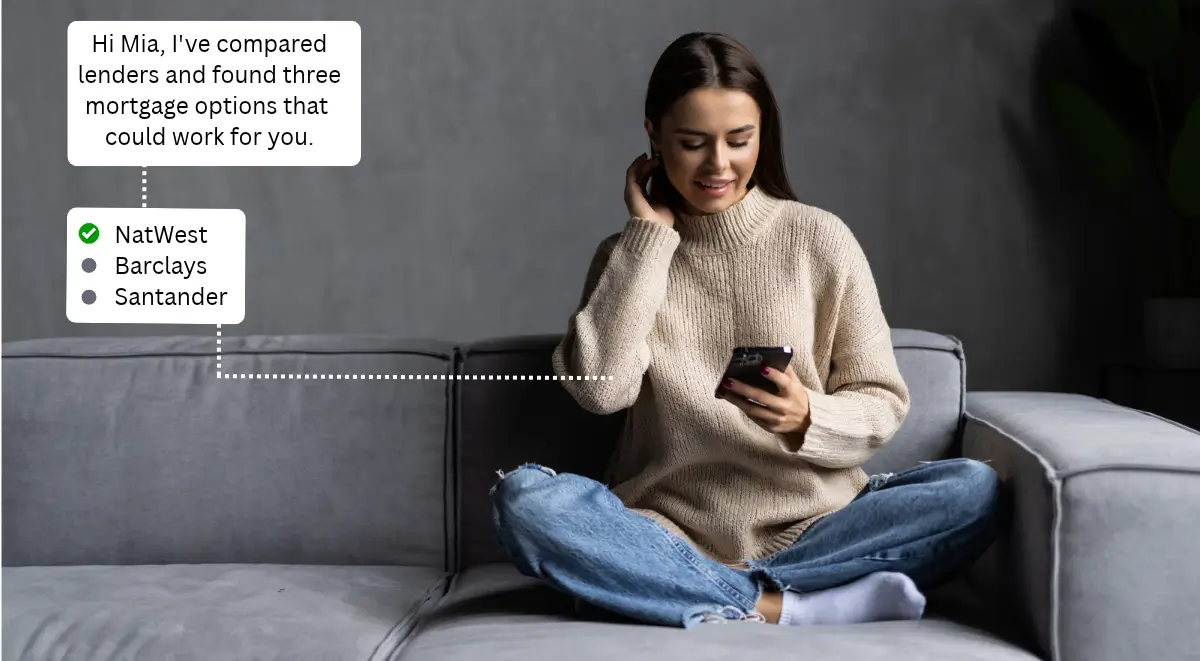
Going direct to one bank shows you a fraction of the market. Compare deals across a representative panel of 50+ UK lenders and get tailored advice from start to finish from FCA regulated mortgage brokers.
- 50+ UK lenders
- No obligation quote
Mortgage Broker vs
Going Direct to a Bank
When arranging a mortgage, you can either apply directly with a single bank or work with an FCA-regulated mortgage broker. While going direct limits you to one lender's products and criteria, using a broker compares multiple lenders side by side and provides regulated advice tailored to your circumstances. Here is how both routes compare:
| Feature | Using a Mortgage Broker (GHL Direct) | Going Direct to a Bank |
|---|---|---|
| Lender & Rate Access | Compares deals across a representative panel of 50+ UK lenders, including broker-only rates | Restricted strictly to that single bank's own mortgage products |
| Criteria & Income Matching | Matches your exact income (employed, self-employed, bonuses, or complex) to lenders with the most favourable rules | Pass-or-fail against one bank's rigid underwriting policy |
| True Cost Calculation | Calculates total cost over the fixed period—factoring in interest rates, product fees, cashback, and free valuations | Only compares internal tiers within that bank's own range |
| Protection of Credit Score | Pre-screens lender criteria before submitting, avoiding unnecessary hard credit searches and declines | A decline leaves a footprint and forces you to start from scratch elsewhere |
| Application & Chasing Support | Dedicated adviser packages your documents and chases underwriters, surveyors, and solicitors to completion | You manage paperwork, upload queries, and follow up through call centres yourself |
| Regulatory Protection | Full FCA-regulated advice—the adviser is legally responsible for recommending a suitable mortgage | Often "execution-only" online, leaving product choice liability on you |
YOUR HOME OR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON YOUR MORTGAGE.
How a Broker Saves You Money Beyond the Headline Rate
The lowest headline interest rate is not always the cheapest mortgage. Arrangement fees, lender incentives, and borrowing limits can swing the real cost of a deal by thousands of pounds over a 2- or 5-year fixed term.
True Total-Cost Analysis
A 4.19% rate with a £1,499 arrangement fee can cost more over two years than a 4.39% fee-free deal on smaller mortgages. We calculate the exact net cost over your fixed period.
Higher Borrowing Safely
Different UK lenders apply income multiples ranging from 4.49x up to 5.5x+ for eligible applicants—and treat overtime, commission, and company profits very differently.
Protect Your Credit Score
Getting declined by a high-street bank because of a minor criteria makes applying elsewhere harder—we verify eligibility upfront to ensure you're ready to apply.
| Mortgage Option | Headline Rate & Fee | 24-Month Repayments + Fee | Net Verdict |
|---|---|---|---|
| Bank Direct Deal A | 4.19% Fixed + £1,499 fee | £24,699 total cost | Looks cheapest on a comparison table, but £1,499 fee outweighs the lower rate |
| Broker-Matched Deal B | 4.34% Fixed + £0 fee (£250 cashback) | £23,310 total cost | Saves £1,389 over the 2-year fixed period despite a higher headline rate |
| Standard Variable Rate (SVR) | ~7.49% Variable (no action taken) | £31,848 total cost | Rolling onto a lender's SVR costs £8,500+ more over 24 months |
The 5 step GHL Direct
mortgage process
From your initial 15-minute discovery call to collecting your keys or switching rates, our step-by-step process takes the guesswork out of getting a mortgage.
01
Affordability review
We review your income, outgoings, deposit or equity, and credit profile to confirm how much you can realistically borrow and what monthly payments look like.
02
50+ lenders
We search thousands of deals across our representative panel of 50+ UK lenders, comparing rates, fees, cashback, and lending criteria side by side.
03
Agreement in Principle
We secure a soft-search Agreement in Principle (AIP) so estate agents and sellers see you are a verified, proceedable buyer without harming your credit score.
04
Application & paperwork
We package your payslips, bank statements, or tax returns cleanly for the underwriter, submit your full application, and track your property valuation.
05
Valuation, offer & protection
We chase your formal mortgage offer, liaise with your conveyancer through to completion, and review your deal again before your fixed rate expires.
Arranging a Mortgage?
Protect Your Home & Income
A mortgage is likely your biggest monthly commitment—putting tailored protection alongside your deal ensures your home and family stay secure if life takes an unexpected turn.

Life Insurance
Pays a lump sum if you die during the policy term. This could help repay the mortgage and support a partner or dependants.

Critical Illness Cover
Pays a lump sum if you’re diagnosed with a condition that meets the policy’s definitions, helping with your mortgage, bills or other costs.
Income Protection
Replaces part of your income if illness or injury prevents you from working, after a waiting period and for the benefit period your policy allows.
Who Benefits Most From
Using a Mortgage Broker?
Whether your finances are straightforward or complex, having a regulated adviser compare criteria across 50+ lenders saves time, avoids costly mistakes, and uncovers options you won't find on a single bank's website.
Why Use a Mortgage Broker? FAQs
Is it cheaper to use a mortgage broker or go direct to a bank?
How much does a mortgage broker charge?
Do mortgage brokers have access to deals I can't get myself?
Will speaking to a mortgage broker affect my credit score?
What is the difference between a tied bank adviser and a multi-lender broker?
How quickly can I speak to a mortgage adviser at GHL Direct?
Authorised & Trusted UK Mortgage Brokers
GHL Direct is a trading style of GHL Network Services Ltd, an Appointed Representative of The Openwork Partnership (authorised and regulated by the Financial Conduct Authority). Firm FCA reference number: 497119
Ready to find out how
much you could borrow?
Speak with a dedicated GHL Direct adviser today. No jargon, no pressure, and appointments available within the hour, 7 days a week.
